Cormac Henderson, co-founder and executive chairman of trusted part exchange partner, Spring, looks at what the remainder of 2025 has in store for the industry.
The UK new homes market is showing signs of cautious optimism. After a turbulent 18 months marked by inflationary pressures, planning bottlenecks and shifting buyer sentiment, some, not all, developers are now remobilising and reporting an uptick in activity. But as we look to the second half of 2025, one thing is clear: success will hinge not just on what we build, but how we sell it.
The data backs this up. According to the latest NHBC figures, completions in Q2 2025 are up 9% year-on-year, but reservation rates remain volatile. Buyers are hesitant, chains are fragile, and conveyancing delays continue to plague the process. In this environment, part exchange isn’t just a convenience – it’s a commercial imperative.
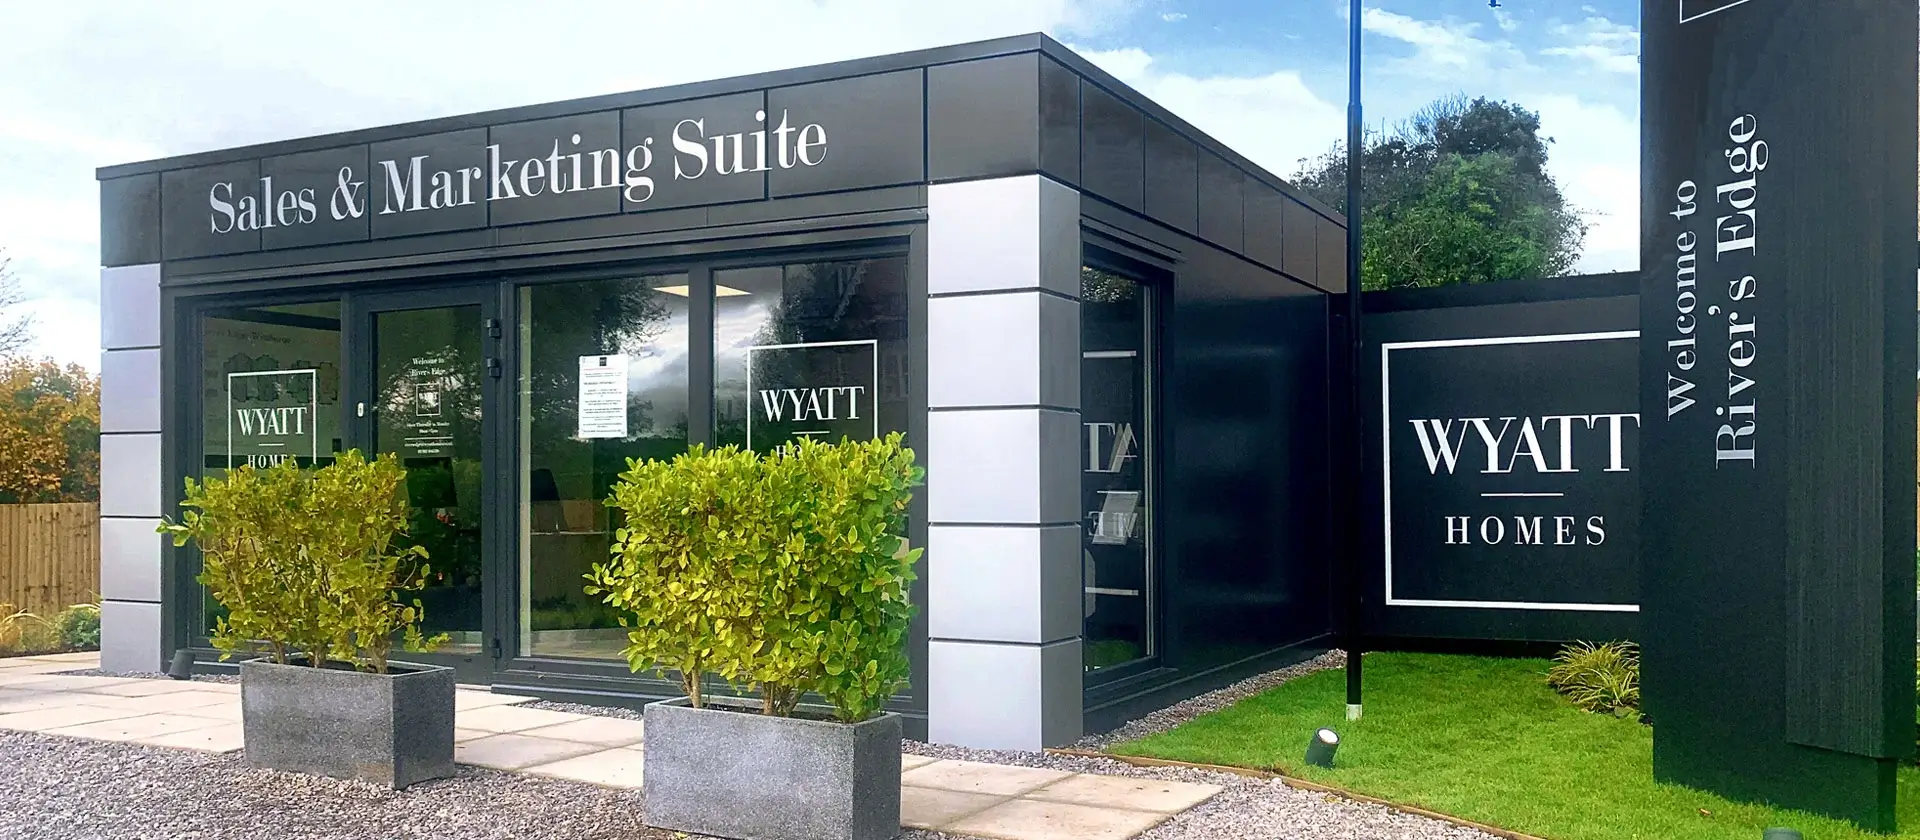
At Spring, we’ve had a front-row seat to the evolving needs of both housebuilders and homebuyers. Our recent partnership with Wyatt Homes is a case in point. By integrating our part exchange (PX) service into their sales strategy, they’ve unlocked a smoother, faster route to completion for customers whether they are upsizing or downsizing.
But what else is happening at the coalface?
Lending
The finance environment for developers remains split. On one hand, we’re seeing a modest thaw in lending conditions, with some high-street banks and specialist lenders re-entering the development finance space after a period of caution. On the other, the cost of capital remains elevated, and funding structures are under more scrutiny than ever. For SME builders in particular, access to affordable finance is still a major hurdle. The Bank of England’s base rate, while stabilising, continues to exert pressure on margins, and lenders are demanding greater transparency on exit strategies, another area where PX can help.
Staffing up
If you have the funds to develop, you’re not in the clear yet – you need the staff to build things out. According to the latest HBF survey, 62% of housebuilders report difficulty hiring qualified staff – up from 48% just a year ago. The problem is particularly acute in regional markets, where competition from infrastructure and retrofit projects is fierce. The government has just announced the launch of a new Council Housebuilding Skills and Capacity Programme to support councils to increase their current levels of housebuilding. This provides a mandate to upskill councils’ existing workforces, recruit and retain graduate talent to specialist positions, which should help to alleviate the situation.
Buyer psychology
Beyond the structural challenges of finance and staffing, developers must also contend with a more complex and cautious buyer mindset. The cost-of-living crisis, while easing, has left a psychological imprint on consumers, many of whom are now taking longer to commit, scrutinising energy efficiency ratings and prioritising flexibility in both design and financing. The rise of hybrid working has also shifted location preferences, with commuter belts expanding and demand for home offices remaining strong. According to Zoopla’s mid-year report, 41% of prospective buyers now rank “adaptability of space” as a top-three priority – up from just 24% in 2022. This means developers must not only build differently but also communicate differently, with messaging that speaks to lifestyle, resilience, and long-term value.
Looking ahead
As we move into the latter half of 2025, there are reasons to be positive. Interest rates are stabilising, planning reforms are (slowly) gaining traction and consumer confidence is beginning to return in certain areas of the country. But challenges remain – from labour shortages to increased sustainability compliance like biodiversity net gain (BNG) – and developers will need every tool at their disposal to stay competitive.